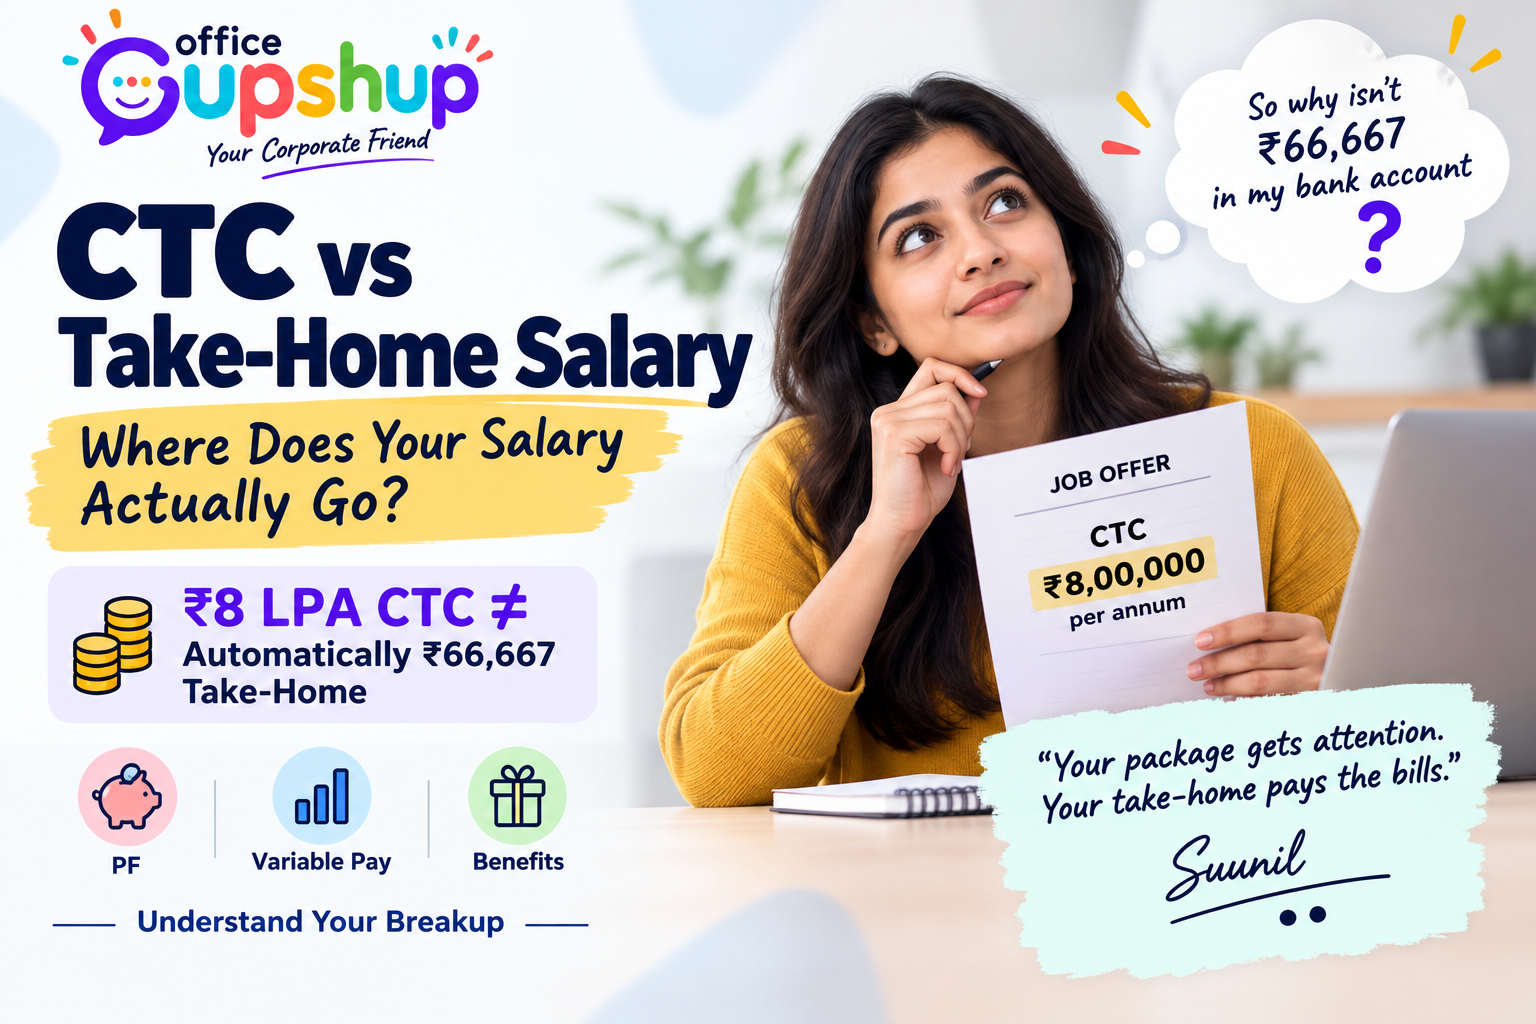
You get a new job offer.
CTC: ₹8 lakh per annum.
Your first instinct is probably:
₹8,00,000 ÷ 12 = ₹66,667 per month.
Nice.
Then your first salary reaches your bank account.
And you stare at the number for a few seconds.
Wait… where did the rest of my salary go?
If you’ve ever wondered why your in-hand salary is much lower than the CTC mentioned in your offer letter, you’re not alone.
And here’s something that may surprise many employees in 2026:
At an ₹8 lakh salary level, income tax may not even be the main reason for the difference under India’s current new tax regime.
The bigger issue is something many freshers discover only after joining their first company:
CTC ≠ Gross Salary ≠ Taxable Salary ≠ Take-Home Salary
Let’s decode your salary slip without turning this into an accounting class.
First: What Exactly Is CTC?
CTC means Cost to Company.
It represents the overall annual cost that an employer associates with employing you.
But here’s the important part:
Your CTC is not necessarily the amount the company will transfer to your bank account during the year.
Depending on the employer and salary structure, CTC can include components such as:
- Basic salary
- House Rent Allowance (HRA)
- Special or other allowances
- Employer’s contribution to Provident Fund (PF)
- Gratuity provision
- Performance-linked or variable pay
- Bonus
- Insurance or certain employee benefits
- Other components included under the company’s compensation structure
Some of these amounts may reach you every month.
Some may be paid later.
Some may depend on performance.
And some may never appear as monthly cash in your bank account at all.
That’s why simply dividing your CTC by 12 can give you a misleading idea of your monthly income.
Think of Your Salary Like This
CTC
↓
Fixed Pay + Variable Pay + Employer-Side Contributions/Benefits
↓
Gross Salary
↓
Employee-Side Deductions
PF + Professional Tax (where applicable) + TDS (where applicable) + other authorised deductions
↓
Your Actual Take-Home Salary
That final number is what reaches your bank account.
So Where Does the Difference Actually Go?
Let’s understand the most common components.
1. Employer PF May Be Included in Your CTC
This is one of the biggest areas of confusion.
Your employer’s PF contribution may form part of the CTC quoted to you.
But that doesn’t mean that amount is additional monthly cash being transferred into your salary account.
At the same time, the employee’s own PF contribution can reduce the amount payable to you as take-home salary.
So there can effectively be two PF-related numbers in a compensation structure:
Employer contribution → may form part of CTC
Employee contribution → can reduce monthly take-home
They are not the same thing.
2. Gratuity Can Be Part of CTC Too
Another common surprise in offer letters is gratuity.
An employer may include an estimated gratuity cost while calculating your CTC.
But that does not mean the same amount is necessarily being deducted from your monthly salary and kept aside in your name.
Gratuity is governed by applicable employment law and eligibility conditions.
For employees comparing job offers, the practical lesson is simple:
Don’t treat every rupee shown under CTC as monthly cash compensation.
3. Variable Pay Can Make a Big CTC Look Bigger
Imagine two offers:
Company A
₹10 lakh CTC
but ₹2 lakh is performance-linked variable pay.
Company B
₹9 lakh CTC
with almost the entire amount fixed.
Which is better?
You can’t answer that just by looking at ₹10 lakh vs ₹9 lakh.
You need to know:
- How much is fixed?
- How much is variable?
- How frequently is variable pay actually paid?
- What performance conditions apply?
- Is the quoted bonus guaranteed?
- How much reaches your bank account every month?
Suddenly, the smaller CTC may look very different.
And don’t make the mistake of comparing your CTC directly with a colleague’s either.
Two people with the same designation can have very different fixed pay, variable compensation, bonuses and benefits.
If you’ve ever discovered that a colleague earns more than you and wondered what to do next, read “How Much Do You Earn?” — Should You Discuss Your Salary With Office Colleagues?.
Salary information is useful only when you’re comparing like with like.
But What About Income Tax?
Here’s where 2026 becomes particularly interesting.
Under India’s current new income-tax regime, the applicable slabs for individuals are:
Up to ₹4 lakh — Nil
₹4 lakh to ₹8 lakh — 5%
₹8 lakh to ₹12 lakh — 10%
₹12 lakh to ₹16 lakh — 15%
₹16 lakh to ₹20 lakh — 20%
₹20 lakh to ₹24 lakh — 25%
Above ₹24 lakh — 30%
But looking only at the tax slabs doesn’t tell the full story.
Eligible resident individuals under the new regime can receive a rebate of up to ₹60,000 where total income does not exceed ₹12 lakh, subject to applicable conditions.
Salaried taxpayers can also get the applicable standard deduction of ₹75,000.
That means an eligible salaried taxpayer with ordinary salary income of up to ₹12.75 lakh can potentially have NIL income-tax liability, after the standard deduction and rebate, subject to the applicable provisions.
There are important exceptions. For example, certain income taxable at special rates can change the calculation.
So if your CTC is ₹8 lakh and your bank account isn’t receiving ₹66,667 every month, don’t automatically blame income tax.
Your salary structure itself could explain a large part of the difference.
PF Rules Have Also Changed in 2026
There’s another reason employees should understand their salary structure now.
The Government has increased the EPFO wage ceiling for mandatory coverage from ₹15,000 to ₹25,000 per month, effective 17 September 2026.
The Government expects the change to bring around 51 lakh additional employees within mandatory EPFO coverage.
But be careful with what this means.
₹25,000 is an EPFO wage ceiling for mandatory coverage. It is not the same thing as saying “anyone earning a ₹25,000 salary will simply lose 12% from take-home.”
The actual PF impact depends on factors including the employee’s applicable wages, existing EPF membership, salary structure and the relevant EPF provisions.
For some employees newly coming within mandatory coverage, however, PF can become another important reason why gross salary and actual bank credit are different.
₹8 LPA Does NOT Automatically Mean ₹66,667 In Hand
This is probably the most important takeaway from this article.
If someone tells you:
“₹8 LPA means you’ll get ₹66,667 every month.”
Don’t rely on that calculation.
₹8 lakh CTC could include employer PF, gratuity, variable pay, insurance or other benefits/components.
Your actual monthly take-home therefore depends on the salary breakup, not merely the headline CTC.
And this is why online “CTC to in-hand salary calculators” should also be treated as estimates unless they use your actual compensation structure.
Before Accepting a Job Offer, Ask HR These 10 Questions
Instead of asking only:
“What is my CTC?”
Ask:
1. What is my annual fixed compensation?
2. What is my monthly gross salary?
3. Approximately what will my monthly take-home be?
4. How much of the CTC is variable pay?
5. What determines whether I receive the full variable amount?
6. Is employer PF included within the quoted CTC?
7. Is gratuity included in the CTC?
8. Are insurance or other benefits included in CTC?
9. What employee-side deductions should I expect every month?
10. Can HR share the complete salary breakup before I accept the offer?
That last question can save you a major surprise on your first payday.
Comparing Two Job Offers? Don’t Compare Only CTC
This is where many job seekers—especially freshers—make a mistake.
Suppose you receive:
Offer A
₹12 lakh CTC
Offer B
₹11 lakh CTC
The obvious answer seems to be Offer A.
But what if Offer A contains a large performance bonus, while Offer B offers substantially higher fixed monthly compensation?
What if one includes several employer-side benefits inside CTC while the other has a cleaner cash-heavy structure?
And what if the lower-paying job gives you substantially better working hours or work-life balance?
We recently explored exactly this trade-off in Should You Take a Lower Salary for Better Work-Life Balance? 7 Questions to Ask Before You Decide.
The bigger CTC is not automatically the bigger monthly salary—or automatically the better career decision.
When comparing offers, look at:
Fixed Pay + Variable Pay + Benefits + Deductions + Actual Monthly Take-Home + Role + Growth Opportunity + Work-Life Balance
The headline number is only the beginning.
Don’t Forget Your Future Salary Either
There’s another mistake people make while comparing offers.
They concentrate entirely on:
“Which company is paying me more today?”
Your current salary matters.
But so does your future earning potential.
A role paying slightly less today may give you stronger skills, better exposure or responsibilities that significantly improve your market value over the next few years.
Similarly, a higher-paying role isn’t necessarily attractive if you’re learning very little and your skills are becoming outdated.
One particularly important factor in 2026 is how effectively professionals are learning to work with AI.
If you’re thinking about which skills could improve your future market value, read Can AI Skills Double Your Salary in India? What Young Professionals Should Learn in 2026.
Your salary today matters.
Your salary trajectory matters too.
Your Offer Letter Is a Financial Document — Read It Like One
Most people spend more time negotiating their CTC than understanding what is inside it.
That’s backwards.
Your compensation structure determines:
- what reaches your bank account;
- what goes toward retirement savings;
- what depends on performance;
- what you may receive only annually; and
- what your employer counts as part of the total cost of employing you.
So the next time HR says:
“We’re offering you ₹10 lakh CTC.”
Don’t immediately calculate:
₹10,00,000 ÷ 12.
Instead, ask:
“Could you please share the complete compensation breakup and approximate monthly take-home?”
That’s not being difficult.
That’s understanding your own money.
The Office Gupshup Take
A job offer isn’t just about getting the highest package.
It’s about understanding what you’re actually being offered.
CTC tells you the overall cost the employer associates with employing you.
Take-home tells you what actually reaches your bank account after applicable deductions.
And your career decision should consider much more than either number:
Role. Learning. Manager. Culture. Stability. Growth. Work-life balance. Fixed compensation. Variable compensation. And yes—actual take-home salary.
So celebrate that new offer.
Just read the breakup before you celebrate the monthly salary.
Got Two Job Offers and Don’t Know Which One Actually Makes More Sense?
One company may be offering the bigger CTC.
Another may offer better fixed pay, role, growth, work-life balance or career potential.
If you’re confused, you don’t have to share confidential company documents.
Share the situation and talk it through with your Corporate Friend.
Book a FREE 10–15 minute Gupshup with Office Gupshup.
Sometimes a second perspective is all you need before making a big career decision.
Office Gupshup | Your Corporate Friend
Disclaimer: This article is for general educational and career-awareness purposes. Salary structures, EPF applicability and income-tax liability vary depending on individual circumstances and applicable laws. For personal tax, payroll or legal advice, consult an appropriately qualified professional.
[…] 👉 Related: CTC vs Take-Home Salary in India: Where Does Your Salary Actually Go? […]
[…] 👉 CTC vs Take-Home Salary in India: Where Does Your Salary Actually Go? […]
[…] 👉 CTC vs Take-Home Salary in India: Where Does Your Salary Actually Go? […]
[…] CTC vs Take-Home Salary: Where Does Your Salary Actually Go? […]